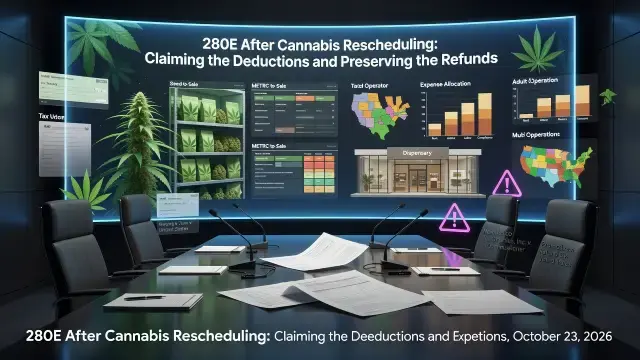
A Federal Bar Association CLE webinar on October 23, 2026, will bring together four tax attorneys to address one of the thorniest questions facing cannabis operators right now: what does federal rescheduling actually mean for a company's tax bill? Harris Sliwoski Managing Partner Vince Sliwoski will lead the session, joined by Ani Galyan of Galyan Law, P.C., and Matthew E. Wright and Kate Roth of Holland & Hart LLP. The panel, titled "280E After Cannabis Rescheduling: Claiming the Deductions and Preserving the Refunds," is built for anyone who touches cannabis tax strategy, whether in-house or advising from outside.
Why 280E Still Matters, Even After Rescheduling
Section 280E has shaped cannabis accounting since the industry's earliest days. The rule denies ordinary business deductions to companies trafficking in a federally controlled substance, which has long meant dispensaries and cultivators pay tax on gross profit rather than net income. That math hits hard. A retailer with thin margins and high rent, labor, and compliance costs can end up with a tax liability that bears little relation to actual profitability.
Rescheduling has not erased that framework, but it has complicated it. Recent federal developments have shifted the calculus for certain medical marijuana operations, opening the door to deductions that were previously off-limits. Adult-use businesses, though, remain squarely inside 280E's reach. For companies that only sell into one market or the other, the distinction is at least conceptually clean. For vertically integrated operators holding both medical and adult-use licenses, it is not. Expense allocation between license types becomes a real operational and legal question, not an academic one.
Allocation, Deductions, and the Practical Headaches
Here's the catch: a dispensary that sells to both medical patients and adult-use consumers out of the same storefront, with shared budroom inventory, shared staff, and a single POS system, cannot simply declare itself "medical" for tax purposes. Costs have to be traced and allocated with some defensible methodology - rent, utilities, inventory handling, even portions of compliance logging tied to seed-to-sale tracking systems like METRC. That sounds tidy on paper, but in practice, operators and their accountants are working with limited guidance on how aggressive or conservative that allocation should be. The webinar's panel will walk through which expenses may now qualify as deductible and how businesses should approach that split without inviting an audit.
The Refund Question: Retroactive Relief and Filing Deadlines
The session's second major thread concerns money already paid. Litigation including New Mexico Top Organics, Inc. v. Commissioner and Kwong v. United States has raised the possibility that operators could seek refunds for taxes paid under the old 280E regime, on the theory that rescheduling changes the legal footing retroactively. Whether that argument succeeds is far from settled. Courts have not resolved the core questions, and filing deadlines for refund claims do not pause while the litigation plays out.
That is where protective refund claims come in. Filing one preserves a business's right to pursue a refund later, even if the underlying legal theory has not yet been validated, without which an operator could lose the right to collect even if the courts eventually rule in the industry's favor. The panel will cover applicable deadlines and strategies for preserving those rights while the legal picture remains unresolved.
Who Should Be Paying Attention
This is not a session limited to tax specialists. Multi-state operators, single-location dispensary owners, wholesale brands, and the accountants and attorneys who serve them all have a stake in how this plays out.
- Operators holding both medical and adult-use licenses need clarity on expense allocation before their next filing cycle.
- Businesses that paid taxes under the pre-rescheduling 280E framework should understand whether protective refund claims make sense for their situation.
- Advisors and in-house finance teams need to track moving deadlines tied to ongoing litigation rather than waiting for final rulings.
Registration for the webinar is available through the Federal Bar Association.